How can struggling city centre locations regain value and marketability?
Following solutions for asset classes such as offices, hotels and data centres, this time in the Valdivia Newsroom we present approaches to counter the decline in visitor numbers and loss of value in city centre commercial property. Owners and developers will generally not be able to tackle this challenge in isolation; joint action with local authorities and associations is necessary. Nevertheless, individual properties can make a difference through innovative usage concepts – and perhaps act as a beacon for their surroundings.
Structural challenges for central commercial locations
Many city centres present a rather bleak picture to visitors, shoppers and residents, according to a recent study1by BBE Handelsberatung: “Deserted pedestrian zones, rising vacancy rates and falling visitor numbers are visible symptoms of structural change – particularly in small and medium-sized towns as well as on the outskirts of major cities – that extends far beyond the retail sector.” The causes are also well documented:
- Online retail now accounts for a significant share of retail turnover. In 2024, this totalled 13.4%, but in some sectors it reached as high as 40%2 – sectors such as fashion, accessories or consumer electronics, which previously tended to be located in central city centres.
- At the same time, consumer behaviour has changed. Shopping remains the primary reason for visiting, yet many people wish to combine this with leisure activities or a visit to a restaurant1 .
- More and more of the remaining residents are moving away, thereby contributing to a further decline in vitality. The causes are not only high or rising rental costs, but also declining residential satisfaction due to an increasingly absent or strained social environment3 .
For the owners of adjacent properties, these developments mean a decline in rental income, a fall in the value of their properties, and increasing difficulties in marketing them and finding exit opportunities. Looking at the asset classes typical of city centres, a recent Bulwiengesa study4identifies opportunities for acceptable returns only in investments in office properties, economy and mid-range hotels, as well as micro-living and senior apartments.
A model for transformation
A comprehensive study by TU Darmstadt5 examines potential solutions in detail. Using the example of Darmstadt city centre, it examines in detail how urban planners, neighbourhood and property developers can increase the utility and attractiveness of such locations, thereby also improving their marketability. In doing so, the study focuses specifically on property owners as key players in a transformation, as revitalisation requires not only the will to make a fresh start, but also fresh capital.
The study complements the overall picture with a detailed analysis. For instance, movement data show a measurable decline in visitors with purchasing power. At the same time, the length of stay is decreasing. In surveys, consumption, amenities, public space and quality of stay are rated as having declined significantly, whilst the cityscape is deemed visually unattractive. The authors identify five areas of action which, when combined, can bring about a reversal:
- Multifunctionality as the key
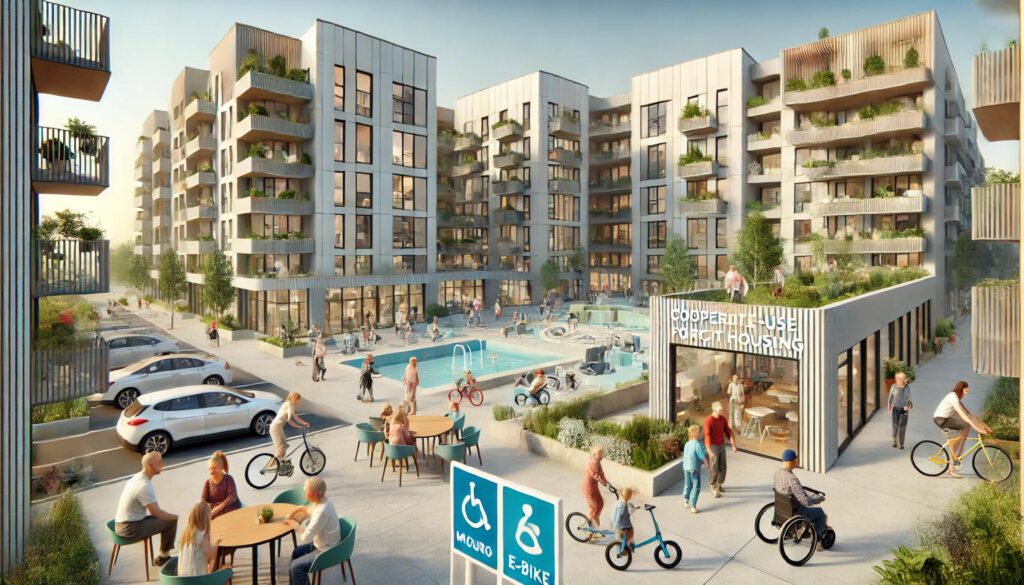
A return to retail alone is not enough; e‑commerce has permanently altered demand too much for that. The solution lies in a mix of uses comprising housing, leisure, social meeting places, work, as well as green spaces and public open spaces. Housing and work in particular revitalise the city centre beyond opening hours and sustainably increase attractiveness and turnover.
- Knowledge work as a driver of footfall
Office and co-working uses are key drivers. Knowledge workers also make above-average use of restaurants, shops and cultural venues, and as many as 42% of those surveyed can also envisage working in the city centre.
- Residential living as the basis for lasting revitalisation
Living in the city centre ensures footfall beyond business hours and boosts amenities in the evenings and at weekends. 20% of respondents would like to live in the city centre, but high rents and poor quality of living act as a deterrent.
- Experiences, leisure and dining
Sports, leisure and cultural facilities increase the length of stay and attractiveness. Many visitors criticise the lack of opportunities for children to move around and play. Additional sports areas, multi-purpose spaces and, in particular, higher-quality dining are seen as key drivers of satisfaction and emotional anchors for a city centre.
- Rethinking shopping
Shopping remains relevant, but is losing its leading role. High-quality product ranges, reliable local amenities and creative pop-up concepts are seen as attractive. For property owners, this creates the strategic task of specifically considering concepts during re-letting that strengthen both the property and its surroundings.
The next steps
Property and space in city centres improve their prospects of success when adapted to a new, sustainable profile of demand and use. However, this transformation can only succeed through the collaboration of all stakeholders. Property owners, trade, tourism and hospitality associations, and local authorities should act in a coordinated manner, jointly develop public spaces and actively promote the regeneration of the property sector. The aforementioned paper by BBE Handelsberatung1 supplements the recommendations in several respects:
- Well-founded, data-driven location analyses are necessary to lay the foundations for the transformation and suitable mixed-use concepts. Social, environmental and mobility aspects must also be taken into account.
- The retail sector in particular needs advice and support to adapt to changing market conditions and customer preferences – for example, through omnichannel strategies and experiential formats.
From the vibrant to the smart city
Digitalisation will also play a role in the revitalisation of city centres, according to a white paper by real estate consultancy Drees & Sommer6 . The cities of the future, the paper argues, are ‘smart’ and connected: ‘The smart city of the future will, as standard, take into account various areas of urban planning and development, using smart data on everything from mobility, healthcare, industry and energy to migration, environmental protection and climate change. An integrated, multidisciplinary and user-oriented approach, in which people are at the forefront, will be essential.’
Concrete starting points on the path to becoming a smart city include data-driven systems, such as intelligent traffic management or a city app that connects retail, hospitality, events and municipal services. Retail in particular can meet customers’ needs through digital services such as up-to-date information on stock availability or flexible collection options. According to the BBE paper1, this requires close “cooperation between the city administration, the retail sector, technology providers and digital platform operators”, as well as the consistent expansion of digital infrastructure.
Conclusion
The future of inner-city commercial property depends less on individual types of use or asset classes than on the quality of their interaction within a resilient, multifunctional environment. Mixed-use development, stable footfall and quality of stay are becoming key factors influencing rental income, suitability for third-party use and exit options.For owners, developers and investors, this means consistently aligning portfolios and projects with a mixed-use profile and viewing their properties as part of the urban fabric. The necessary transformation is based on a willingness to invest, robust data and cooperation with all stakeholders involved. The aim is to strategically develop usage concepts, take digital infrastructure into account and realistically assess long-term demand trends . This not only makes it easier to market individual properties. At the same time, it strengthens the resilience of the entire location, with owners becoming co-creators of a liveable and economically robust city centre.
Sources
- “The Future of City Centres – How Structural Change is Redefining Urban Space”, BBE Retail Consultancy, July 2025
- “HDE Online Monitor”, German Retail Association – HDE e. V., 2025
- Andreas Pfnür, Fabian Lachenmayer, Yassien Bachtal: “City, Country, Suburb: How the Reassessment of Urbanity is Changing Housing – An Empirical Study of Private Households”, Technical University of Darmstadt, Working Papers on Real Estate Research and Practice, Volume No. 54, January 2024
- “The 5% Study 2025 – Where Investment is Still Worthwhile”, Bulwiengesa, September 2025
- Andreas Pfnür, Maria Günther, Jonas Rau: “Real Estate Transformation of Darmstadt City Centre”, Technical University of Darmstadt, Working Papers on Real Estate Research and Practice, Volume No. 59, July 2025
- “10 Theses on the Future of the Construction and Real Estate Industry”, Drees & Sommer Innovation Centre, 2023
(Image source: istockphotos.com)